

Picture this. You have a holiday you booked in the United Kingdom, and you misplace a large sum of money. It was not stolen from your hotel room. You lacked a medical emergency. The money vanished because you were playing the zeppelincrashgame, a high-stakes online betting game. Might your travel insurance compensate that loss? The answer isn’t simple. It relies entirely on the small print in your policy, how UK law defines gambling, and the exact details of what happened. This article analyzes those layers. We’ll move past the initial shock to a practical review of contracts, exclusions, and the real chance of getting a claim paid. We’ll examine what the insurance company would likely say, what arguments a customer might try, and what this means for anyone combining new digital entertainment with travel.
Understanding the Zeppelin Crash Game System
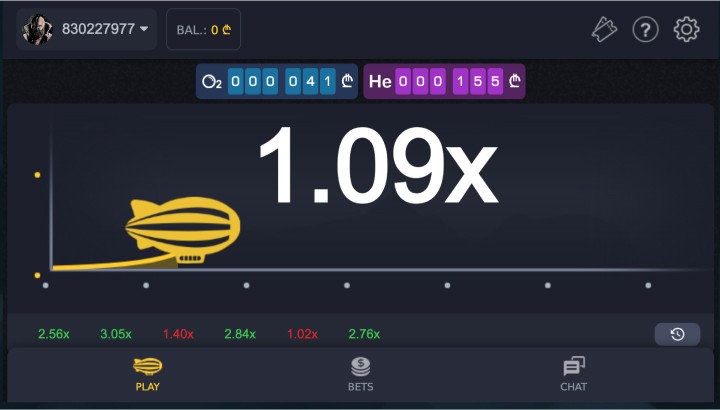
To judge an insurance claim, you need to know what the loss actually is. The Zeppelin Crash Game is an online betting game that uses cryptocurrency. Players make a bet on a multiplier tied to an animation of a rising zeppelin. The game operates until the zeppelin “crashes” at a random moment, determined by a provably fair algorithm. To win, you need to cash out before the crash and collect your multiplied stake. If you’re too slow, you forfeit everything you put into that round. The game is tense and can deliver big returns, but its core is evident: it’s gambling. It’s a game of chance, not skill, where you stake money on an uncertain outcome. Under UK law, this is subject to gambling regulations regulated by the Gambling Commission. That means any financial loss is, first and foremost, a gambling loss. This classification is the greatest single barrier to any travel insurance claim. The fact the game uses crypto introduces a layer of complexity, but it does not alter its basic legal nature in the UK.
The Critical Importance of Policy Wording and Disclosure
Any effort to claim relies solely on the specific wording of that person’s travel insurance document. It is crucial to get and read the full policy wording before you buy the insurance, and definitely before you seek to make a claim. You must search for the exact phrasing of the gambling exclusion. Some older policies might have narrower exclusions, perhaps only mentioning “in a casino” or “on-track betting,” but this is infrequent now. More modern policies often clearly name “online gambling” or “interactive gambling services.” The definition of “loss” also matters. Does it only mean physical cash, or does it include digital currency transfers? When applying for insurance, companies sometimes ask about high-risk activities. If you didn’t reveal frequent or high-stakes gambling when asked, the insurer could conceivably void the entire policy for non-disclosure. That would invalidate any other claims from your trip. The policyholder has the responsibility of proving their claim matches the policy terms. Any argument must be constructed carefully around the precise language in the document, not on a general feeling of unfairness.
Broader Implications for Trip and Novel Digital Risks
This situation shows a expanding gap between conventional insurance and the new digital risks travelers face. A current holiday often entails ongoing digital activity, from managing cryptocurrency wallets to engaging in online games. Standard travel insurance was created for physical problems like lost luggage or a hospital visit. It struggles to categorize and respond to these non-physical, behaviour-driven financial losses. The takeaway for consumers is substantial: standard insurance is not a safety net for risky financial activities, no matter how they are presented as games. The responsibility falls on the passenger to realise that activities like the Zeppelin Crash Game sit entirely outside the scope of travel risk protection. This may spark a conversation about whether specific insurance products could ever cover such losses. The inherent moral hazard and the challenge of valuing the risk make this unlikely. For the near future, the line continues distinct. Travel insurance covers against certain unforeseen events that affect a trip. It does not underwrite your betting decisions, regardless of the platform or the game’s theme.
Usual Travel Insurance Policy Exclusions for Gambling Losses
We must examine the typical exclusions in a UK travel insurance policy. Almost all of them include explicit clauses that refuse to cover losses from gambling or betting. The language is generally broad and offers little ambiguity. A common example excludes “any loss resulting from gambling, betting, or wagering of any kind, including the loss of money or valuables in such activities.” This language seeks to encompass everything: casino games, sports bets, lottery tickets, and, by logical extension, online chance games like Zeppelin Crash. Insurance companies reason that covering gambling losses poses a moral hazard. It would encourage risky behaviour by offering a financial backup plan. They also consider gambling as a voluntary financial speculation, not an unforeseen accident in the usual sense of insurance. The insurer’s position would be straightforward: the customer opted to take part in a known risky activity and took on the risk of loss. This exclusion represents the most robust part of an insurer’s defence. It leaves a successful claim for the direct gambling loss extremely improbable, and most likely impossible.
Practical Steps Following a Major Gambling Loss Abroad
What should a traveller do if they suffer a crippling financial loss from something like the Zeppelin Crash Game while on a UK-booked holiday? The immediate steps are realistic and measured. First, confirm you are protected and have basic welfare covered. Get in touch with friends or family for emergency support if you require it. Tell your tour operator or hotel if you might not be able to pay your expenses, as they may have hardship procedures. Second, about insurance, study your policy wording thoroughly before you call the insurer. Count on a quick rejection based on the gambling exclusion. Filing a claim anyway creates a formal record, which you require if you later go to the Financial Ombudsman Service. But maintain your expectations low. Third, seek independent advice from a citizen’s advice bureau or a consumer rights lawyer. They will most likely confirm the exclusion is legally solid. Fourth, explore contacting the Gambling Commission if you believe the gaming platform itself was unfair or illegal. Finally, treat this as a hard lesson in separating risks. Money you employ for speculative entertainment should be isolated from your essential travel funds. Never count on it to pay for your trip.
Regulatory Environment and the Financial Ombudsman Service
If an insurer rejects a claim for a Zeppelin Crash Game loss, the policyholder in the UK can bring the case to the Financial Ombudsman Service (FOS). The FOS resolves disputes based on what is “fair and reasonable.” They consider good industry practice, not just the strict legal terms. Past FOS decisions on gambling and insurance reveal a clear pattern. The Ombudsman consistently supports gambling exclusions as valid and enforceable, as long as they were clearly communicated in the policy. The FOS is not likely to require an insurer to pay for a voluntary gambling loss. They might, however, verify if the exclusion clause was prominent and easy to understand. If the wording was unusually vague or the insurer processed the claim poorly, the FOS could award some compensation for distress. This wouldn’t compensate for the gambling loss itself. The regulatory framework therefore reinforces the insurer’s stance. The Gambling Commission separately regulates the game operators, focusing on fairness and preventing harm, not on insuring player losses.
Likely Claim Avenues and Their Feasibility
A direct claim for the lost bet will nearly definitely fail. But a policyholder could look at different, less direct angles in their policy wording. One might argue, for example, that the distress from the loss caused a medical or psychological issue needing treatment abroad. This might try to trigger the medical expenses section. Insurers would most likely fight this on causation. Many policies also exclude conditions that result from illegal acts or deliberate risk-taking. Another approach might involve theft or fraud. If someone hacked the game platform or stole funds during a transaction, this could possibly fall under a “loss of money” section. This assumes the policy doesn’t have a gambling exclusion that overrides it. Proving the loss was due to criminal action rather than the normal game mechanics would be a tough evidential hurdle. A marginally more plausible, though still difficult, argument could involve “cancellation or curtailment.” If the gambling loss left the traveller completely penniless and physically unable to continue the holiday, forcing an early return home, they could try this. Even then, insurers would focus on the voluntary nature of the loss and point to the gambling exclusion.
Contrasting Travel Insurance with Gambling Consumer Protections
It aids to evaluate the purpose of travel insurance with the consumer protections in the UK’s regulated gambling industry. Travel insurance is a contractual product that insures particular risks and has defined exclusions. The Gambling Commission’s system, on the other hand, centers on licensing operators, ensuring games are fair, protecting vulnerable people, and offering routes for self-exclusion and complaints. Some protections, like deposit limits, are preventative. If a player believes the Zeppelin Crash Game operator acted unfairly or broke its licence rules, they can file a complaint to the operator, then to an Alternative Dispute Resolution (ADR) scheme, and finally to the Gambling Commission. But none of these channels will refund losses just because a bet lost. They address procedural unfairness, not the risk of the market. This split highlights a basic truth: travel insurance and gambling regulation exist in separate worlds. One does not compensate for the limits of the other. A traveller’s loss from a crash game, unless there was operator malpractice, is a personal liability. It’s a risk taken knowingly in a regulated but unforgiving market.
The role of self-discipline and hazard control

This examination always reverts to personal responsibility. Journey protection exists to soften the blow of unanticipated, often forced troubles—like a burglary, an disease, or a abrupt weather event. Opting to engage in a high-stakes betting game like Zeppelin Crash is a anticipated economic danger. You take part in it by choice, aware you could lose everything. The game’s appeal relies on that danger. Anticipating an coverage plan, paid for by all insured parties, to bear the repercussions of such a decision opposes the basic idea of mutual protection against typical risks. Effective risk management for today’s traveller means setting a firm distinction between budget for journey safety and budget for amusement betting. It means reviewing the limitations in an coverage agreement as the true extent of what’s insured, not just detailed terms. In the UK’s legal and regulatory framework, the difference between protected incident and uninsured speculation remains clear. The Zeppelin Crash Game scenario is a stark illustration of this divide. Some hazards, no matter how virtual their presentation, remain solidly with the player who takes them.